
Evidence Across Stock & Bond ETFs
For several years now, a meaningful part of our public research has focused on intraday trading frameworks, highlighting their potential as effective diversifiers alongside traditional investment vehicles.
In parallel, our day-to-day practice has consistently moved toward a deeper understanding of why intraday trends form, while also refining the methods we use to capture them.
Even though we cannot disclose the full extent of our findings, every now and then we come across insights that we believe are worth sharing with our community of readers.
Today, building on our research into institutional rebalancing activity and its impact across equity and fixed-income markets, we document how anticipating such flows can enhance the effectiveness of intraday trend signals.
To investigate this relationship, we apply a simple trading framework to two liquid ETFs (SPY and TLT) from January 2008 through August 2026, and show that the expected rebalancing flows between the two can materially influence the profitability of intraday trend setups.
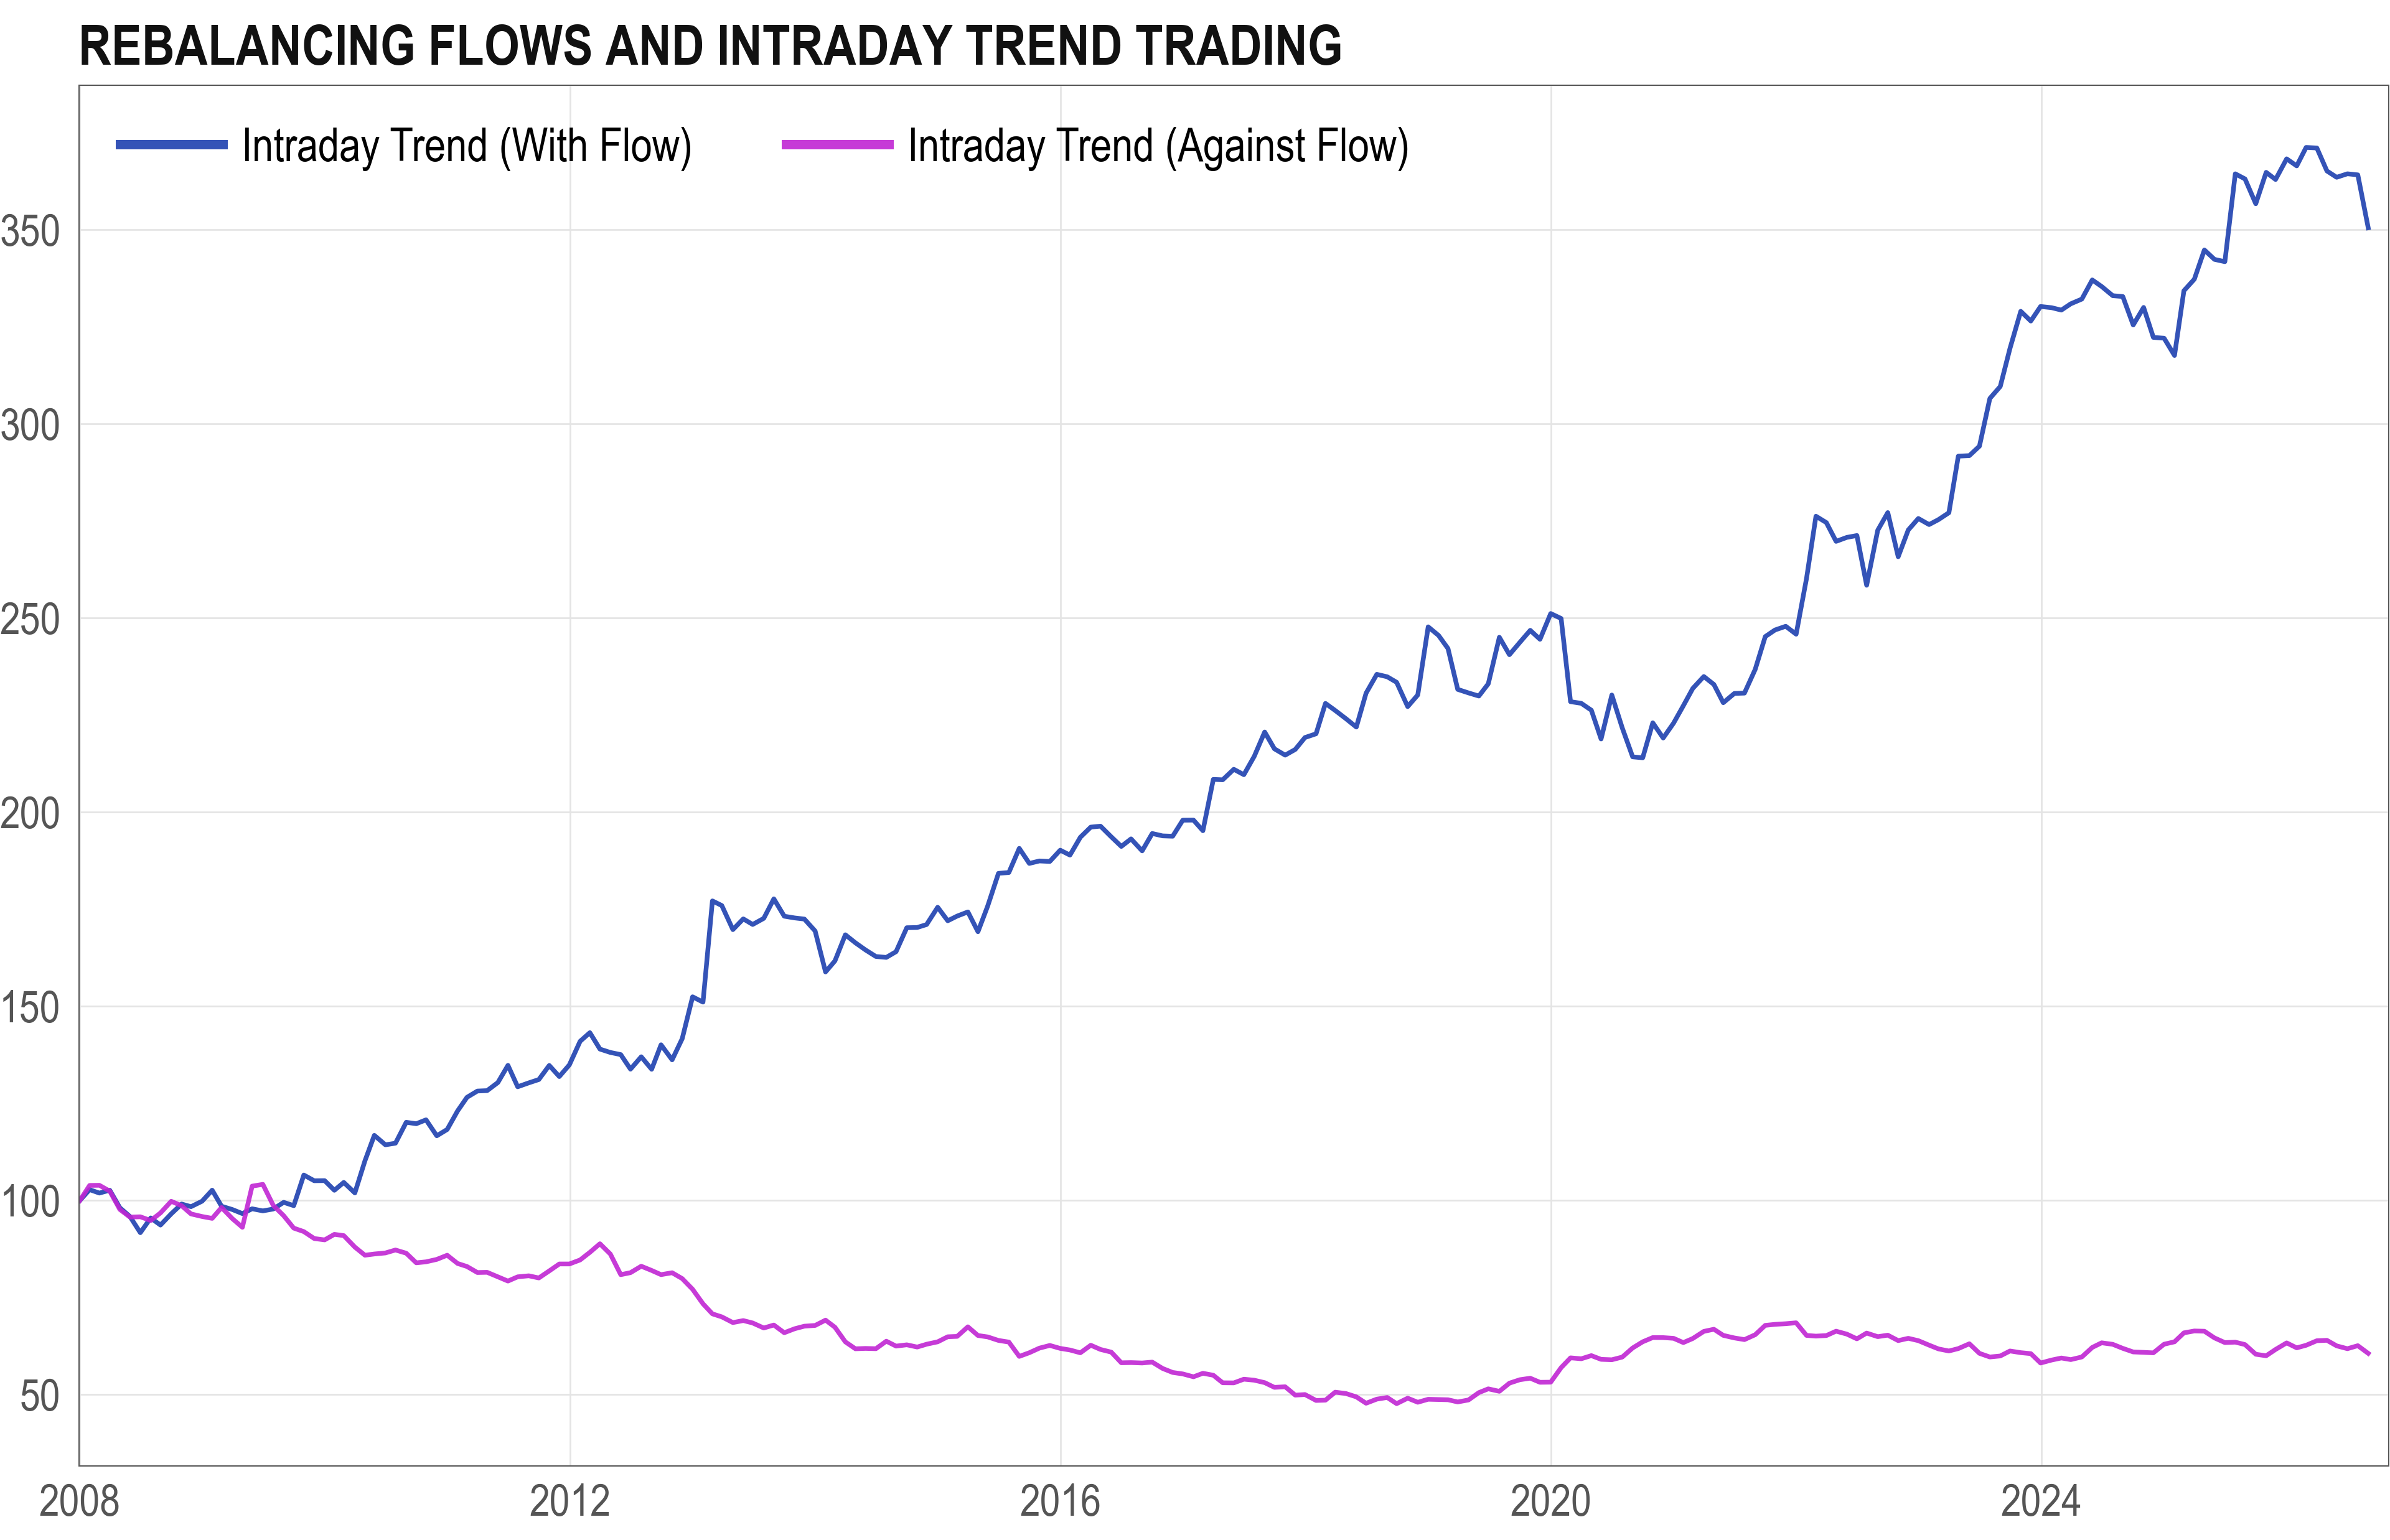
In the following sections, we take a closer look at how we can interpret these results, while also outlining the full methodology behind our tests and the trading rules underlying our strategy.
Premium article
Read the full article
Buy this article on its own, or subscribe on Substack to read it together with all our premium research.
Questions about buying or your order? Email [email protected]