
Additional Evidence and Strategy Refinements for a SPY/TLT Model
Earlier this month, we published “How to Generate Alpha From Rebalancing Flows”, a piece that sparked considerable interest among our readers.
As it turns out, investors are becoming increasingly receptive to the idea that technical flows of large market participants (such as pension funds, sovereign-wealth funds, and other institutions) can produce meaningful price anomalies.
This phenomenon also fits within a much broader theory of how modern markets function, as mechanically directed capital has (and continues to) become more pervasive.
For readers who wish to explore the subject in greater depth, we highly recommend listening to this episode of The End Game, where Michael W. Green (Founder, CEO, and CIO of Tier1 Alpha Asset Management), offers valuable insights to understand how passive investing has become a fundamental force in shaping market behavior.
Inevitably, this discussion brings us back to our original framework and motivates us to seek further evidence that the effects we identified (and showed how to harvest) are genuinely associated with common stock-and-bond rebalancing practices.
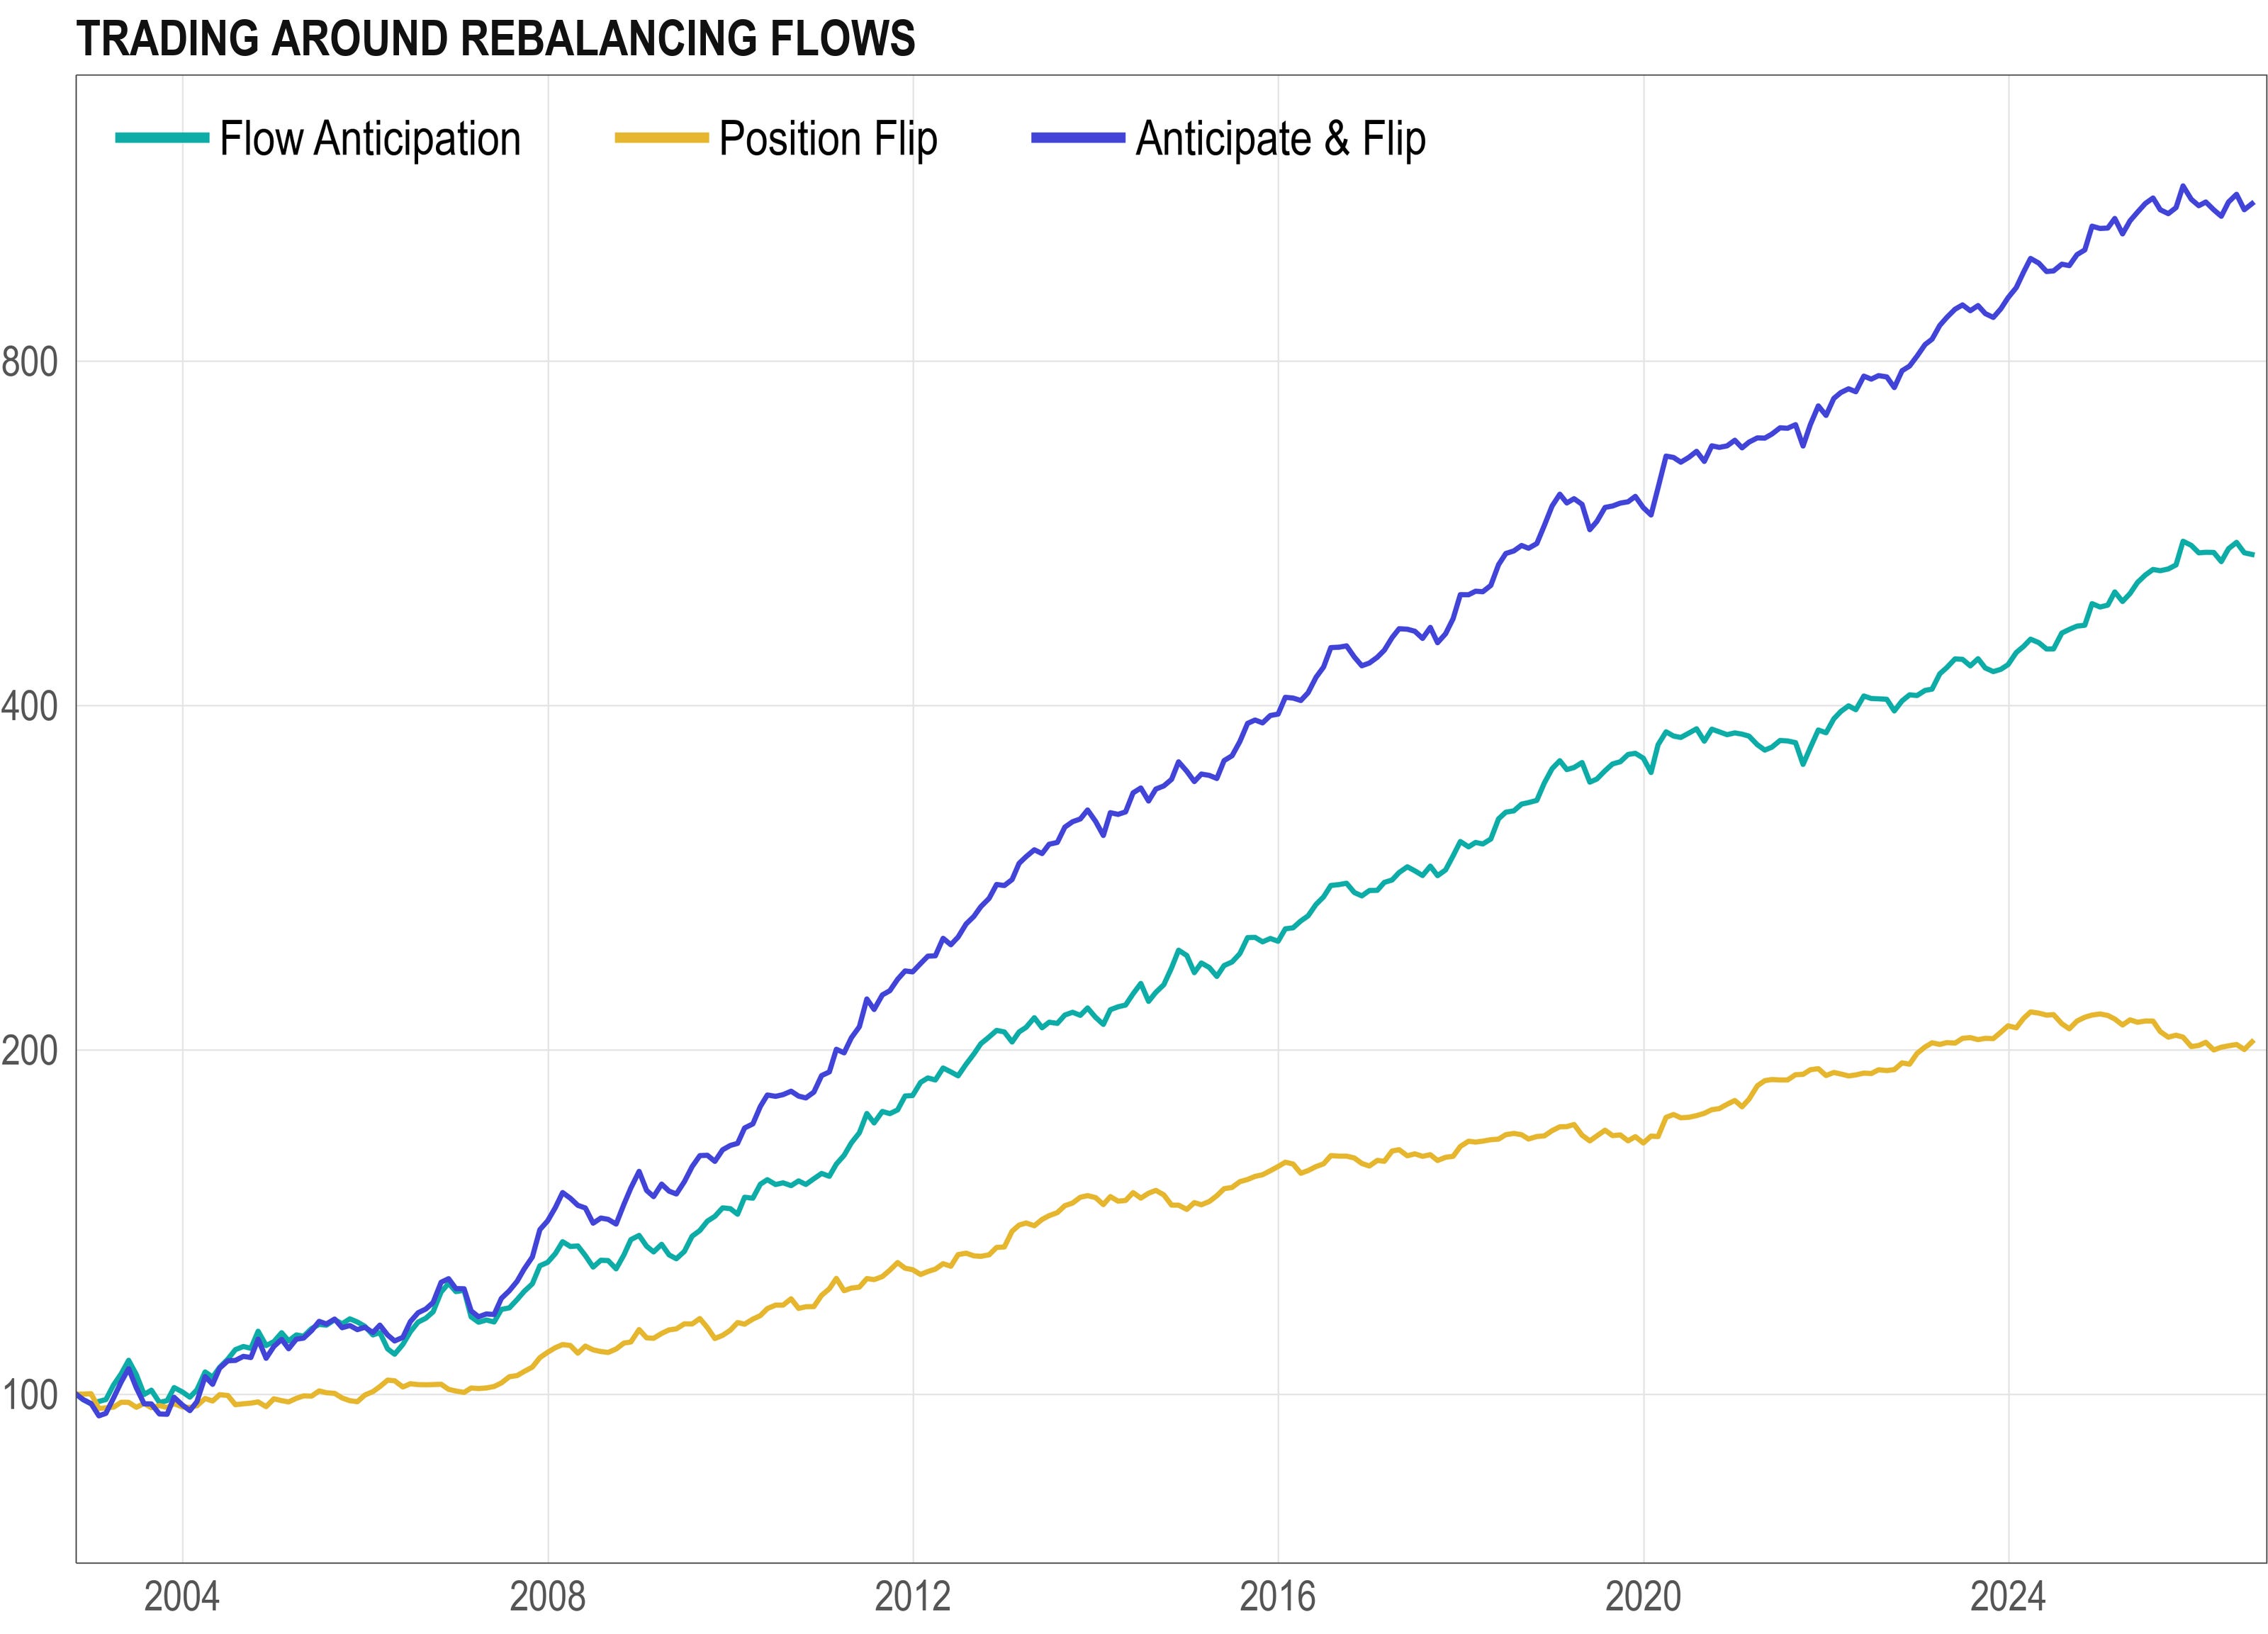
In this article, we also introduce a smart refinement to our base strategy. From November 2002 through August 2026, the new variant recorded a net-of-fee Sharpe ratio of 1.33 and a CAGR of 10.6%, while keeping average exposure and risk in line with its original implementation.
Premium article
Read the full article
Buy this article on its own, or subscribe on Substack to read it together with all our premium research.
Questions about buying or your order? Email [email protected]