
Revisiting Andreas Clenow’s Classic CTA Model, from Futures to ETFs
Anyone who has dug into quantitative trading has almost certainly come across the work of Andreas Clenow.
In our view, since “Following the Trend” first came out in 2013, Andreas has been one of the most prolific and valuable contributors to the field, earning a particularly loyal readership among our community.
With that in mind, we thought it would be worth revisiting his core trend strategy and seeing how it performs under our own portfolio construction methodology.
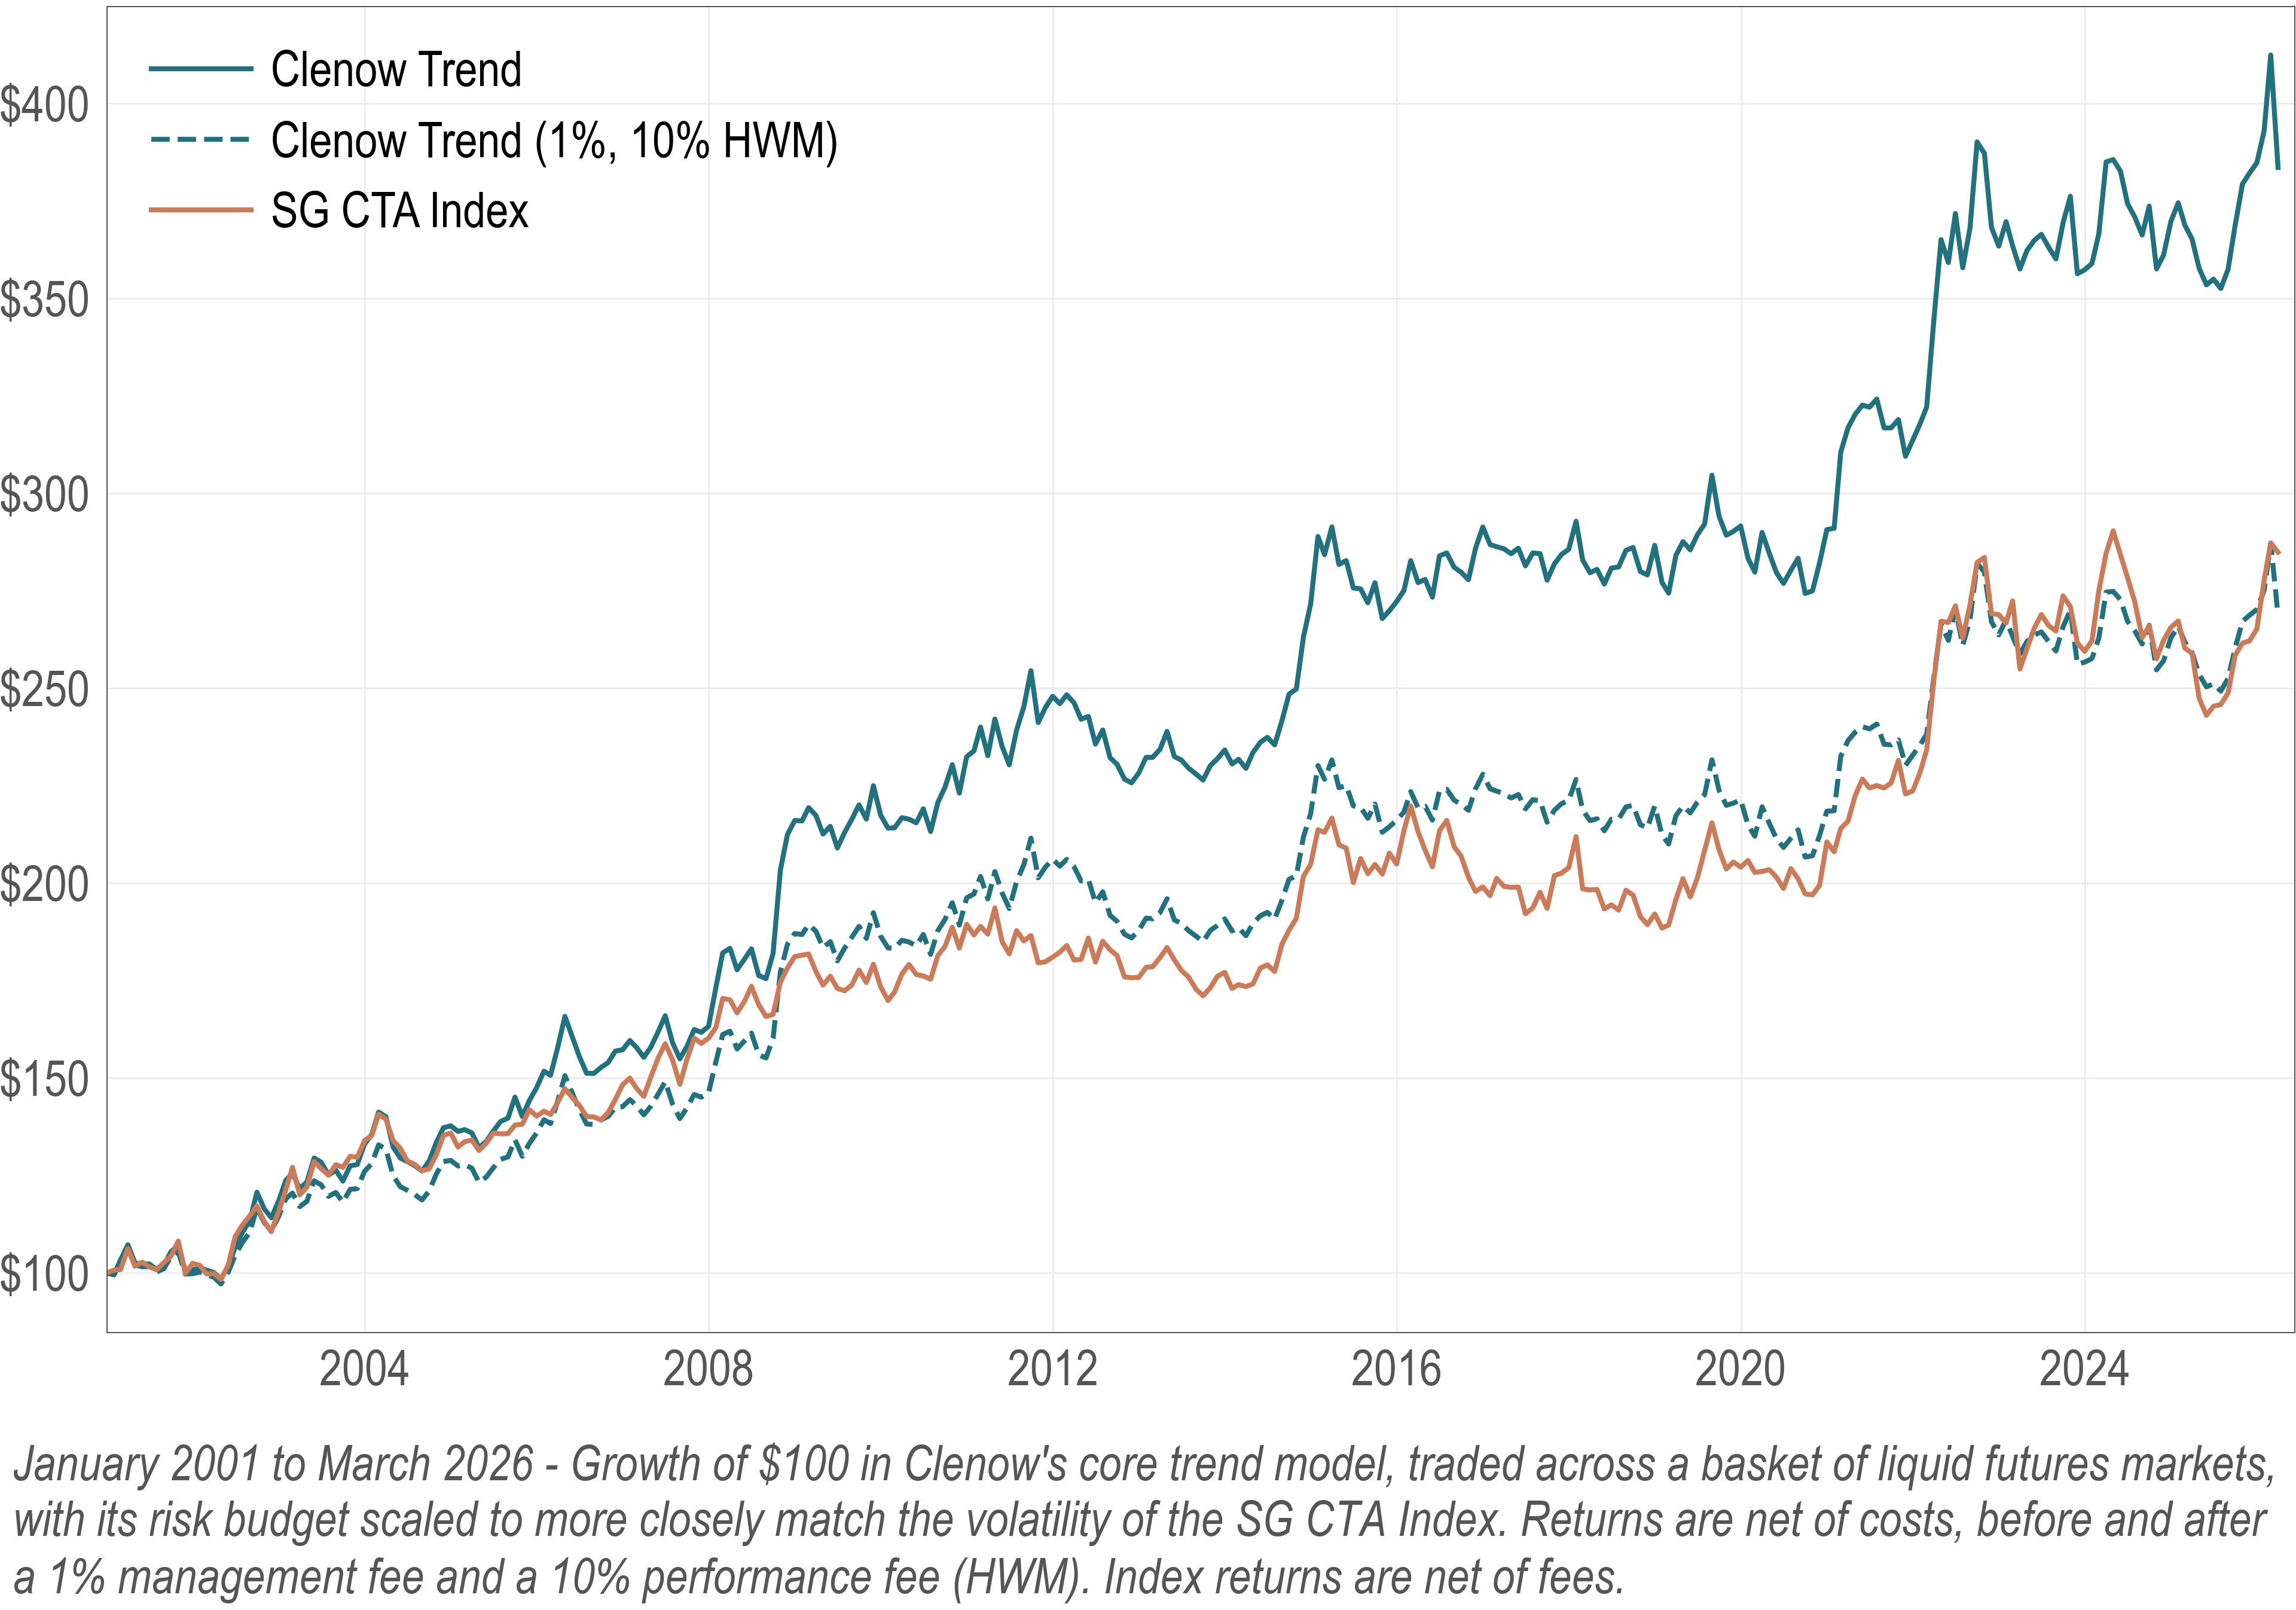
Our tests show that, net of costs, this approach has historically outperformed the SG CTA Index, both in absolute and risk-adjusted terms… and can still look competitive after typical management and performance fees.
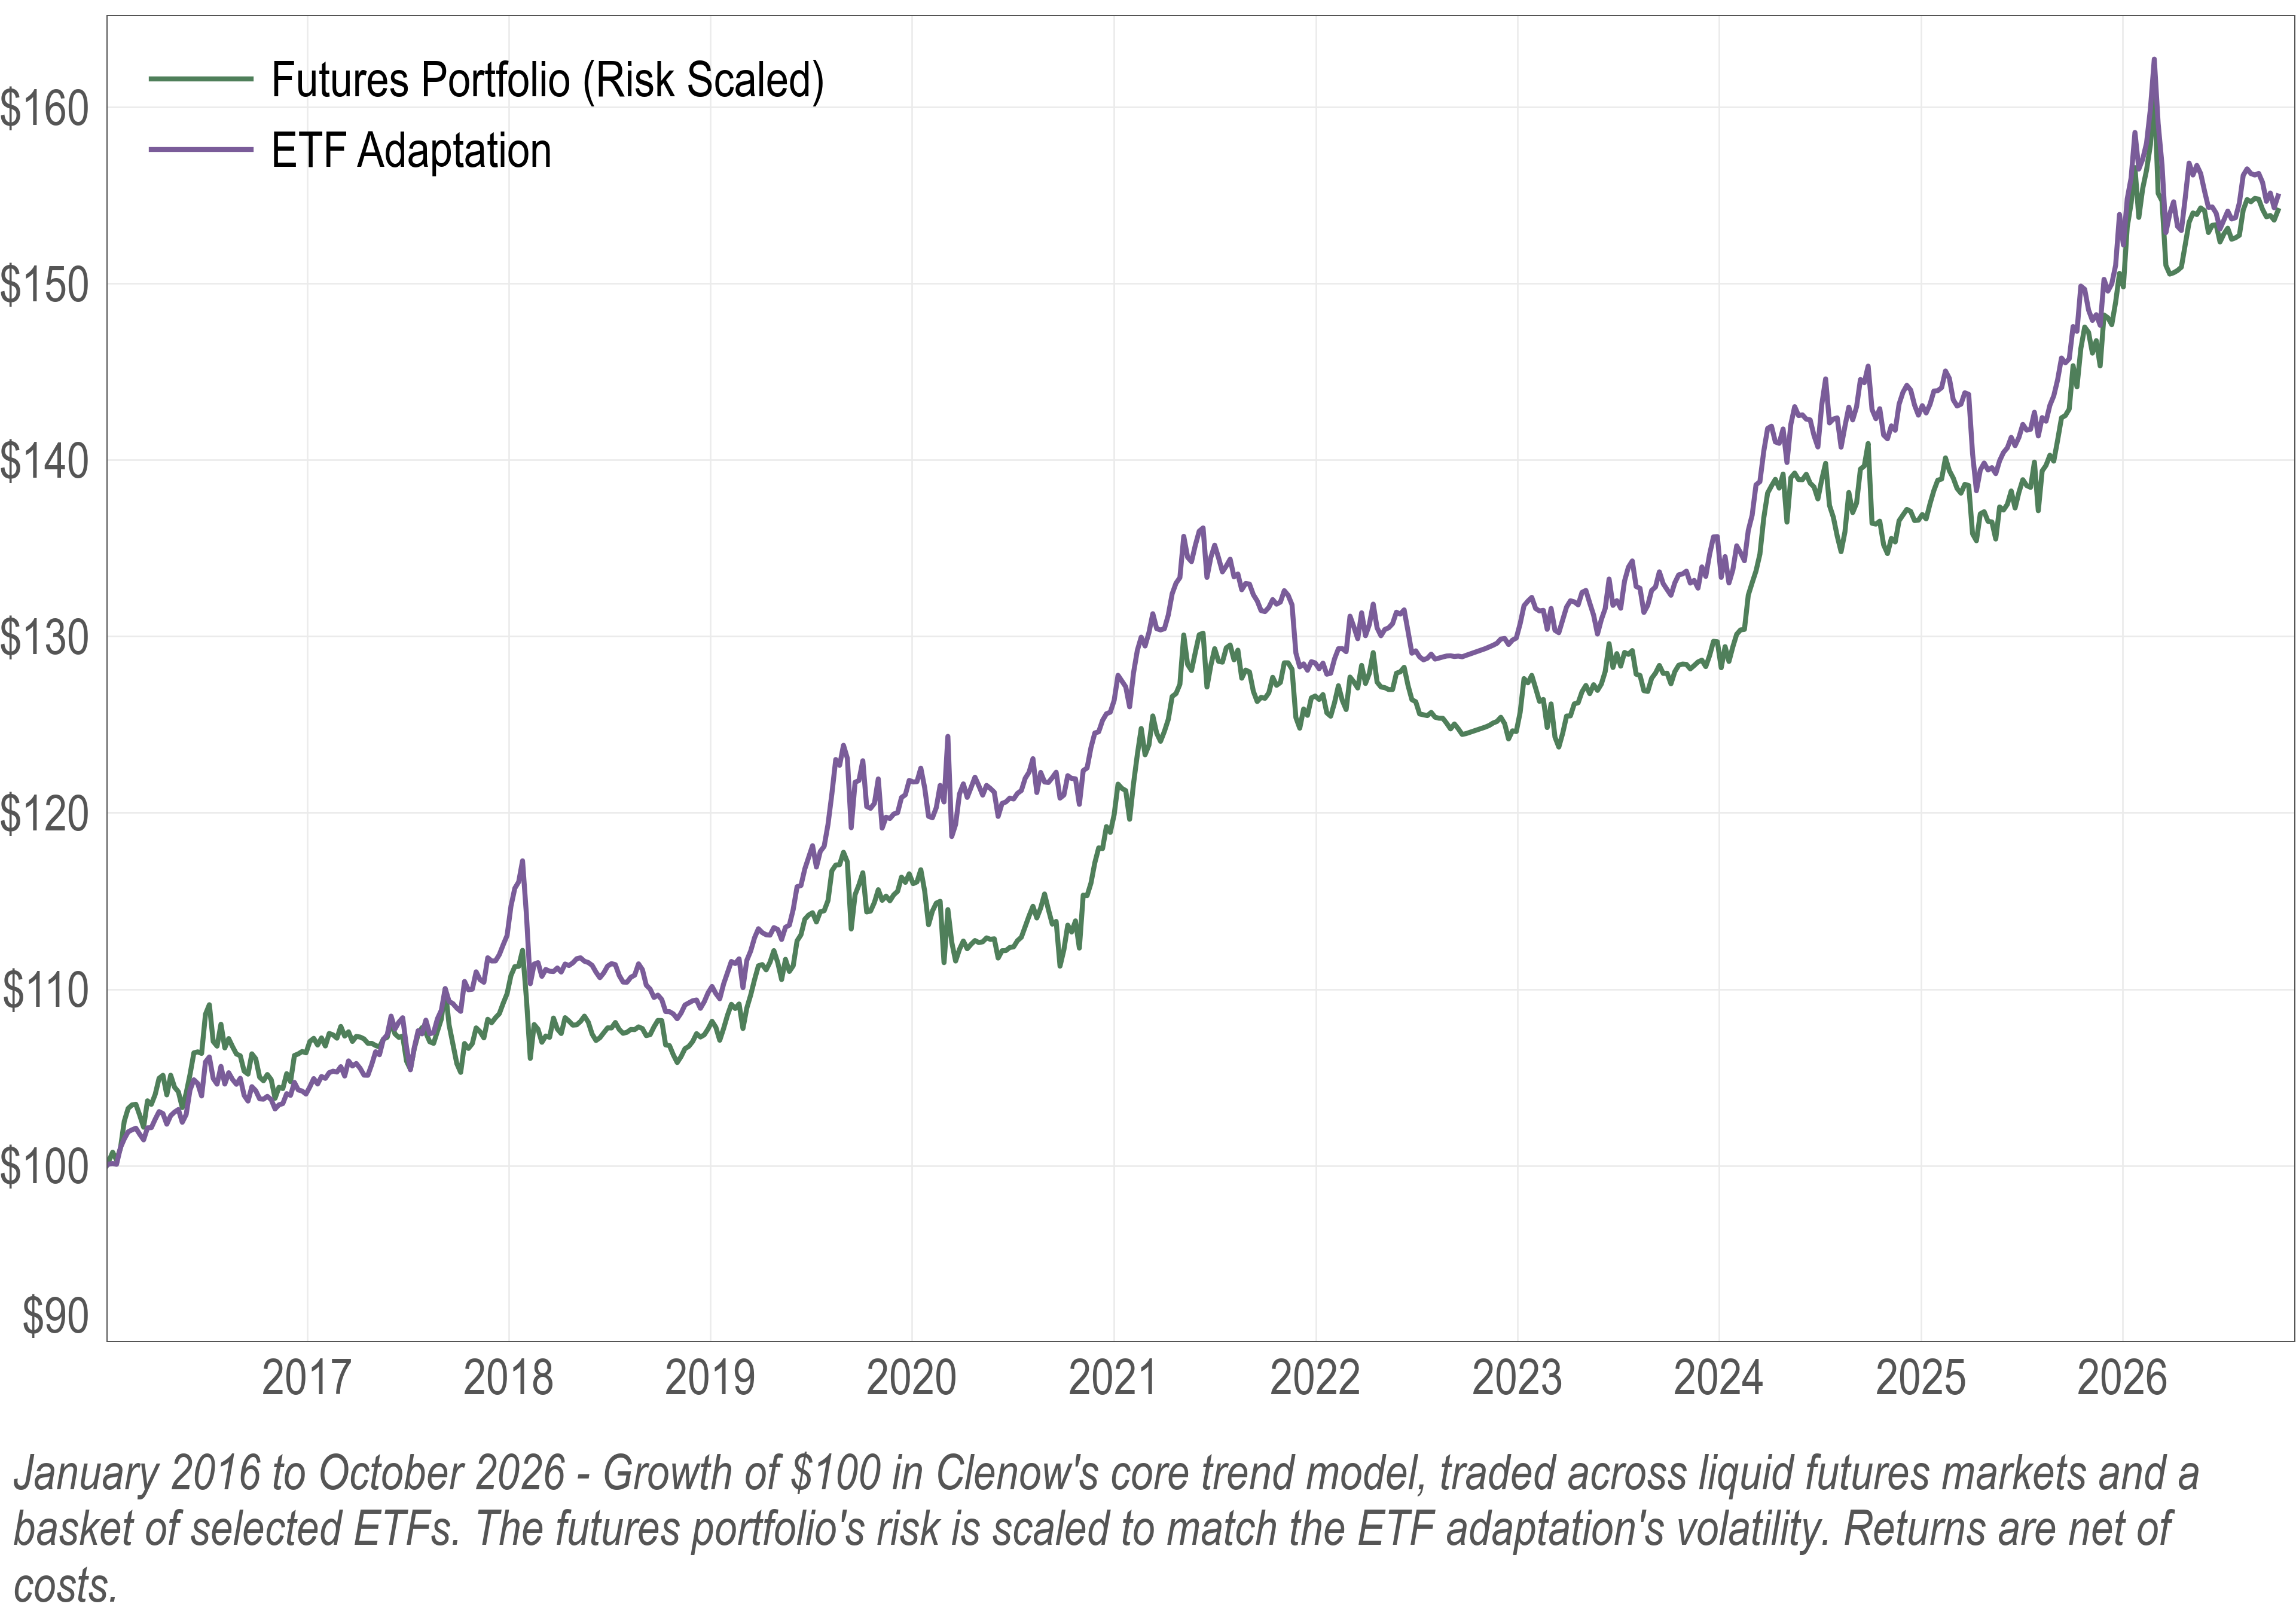
After walking through the rules, we will also show how to adapt and implement the strategy via ETFs, covering every step of the process, from ETF selection to some practical considerations worth keeping in mind.
Core Trend Model
We begin by laying out the rules of Clenow’s core trend strategy, as described in the second edition of Following the Trend (2023), defining when to enter and exit positions, and how to estimate each market’s risk.
Portfolio construction, on the other hand, is our own, from the choice of contracts to trade to how risk is allocated across them.
Premium article
Read the full article
Buy this article on its own, or subscribe on Substack to read it together with all our premium research.
Questions about buying or your order? Email [email protected]