
A Market-Neutral Approach for Dynamic Factor Investing
Last week, drawing on a very insightful piece by Man AHL (“A Trend Following Deep Dive: Cash (Equities) Is King”), we investigated the presence of both cross-sectional and time-series momentum effects within a basket of fifteen US factor portfolios, constructed using Professor Kenneth French’s publicly available data library.
While our findings are consistent with those of Panjabi, Bordigoni, and Buchanan (2026), they should not be viewed as direct confirmation that such actively managed factors can be traded directly as constructed.
Implementing long-short equity portfolios presents several practical challenges, and although transaction costs remain an important consideration, today we specifically focus on short-selling, which constitutes a significant (and less discussed) pain-point.
In particular, we present an alternative implementation of our original study, built to offer a more practical (and scalable) version of the factors we previously examined.
Our results suggest that momentum effects persist under alternative factor-construction techniques that, over the last twenty years, would have still proven effective in isolating exposure to the best-performing equity styles.
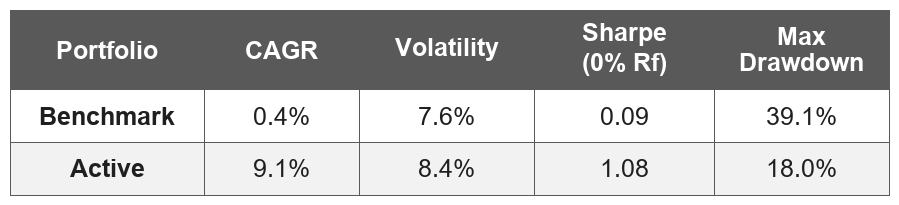
As the numbers above highlight, our actively managed framework helps revive an otherwise stagnant blend of factor portfolios.
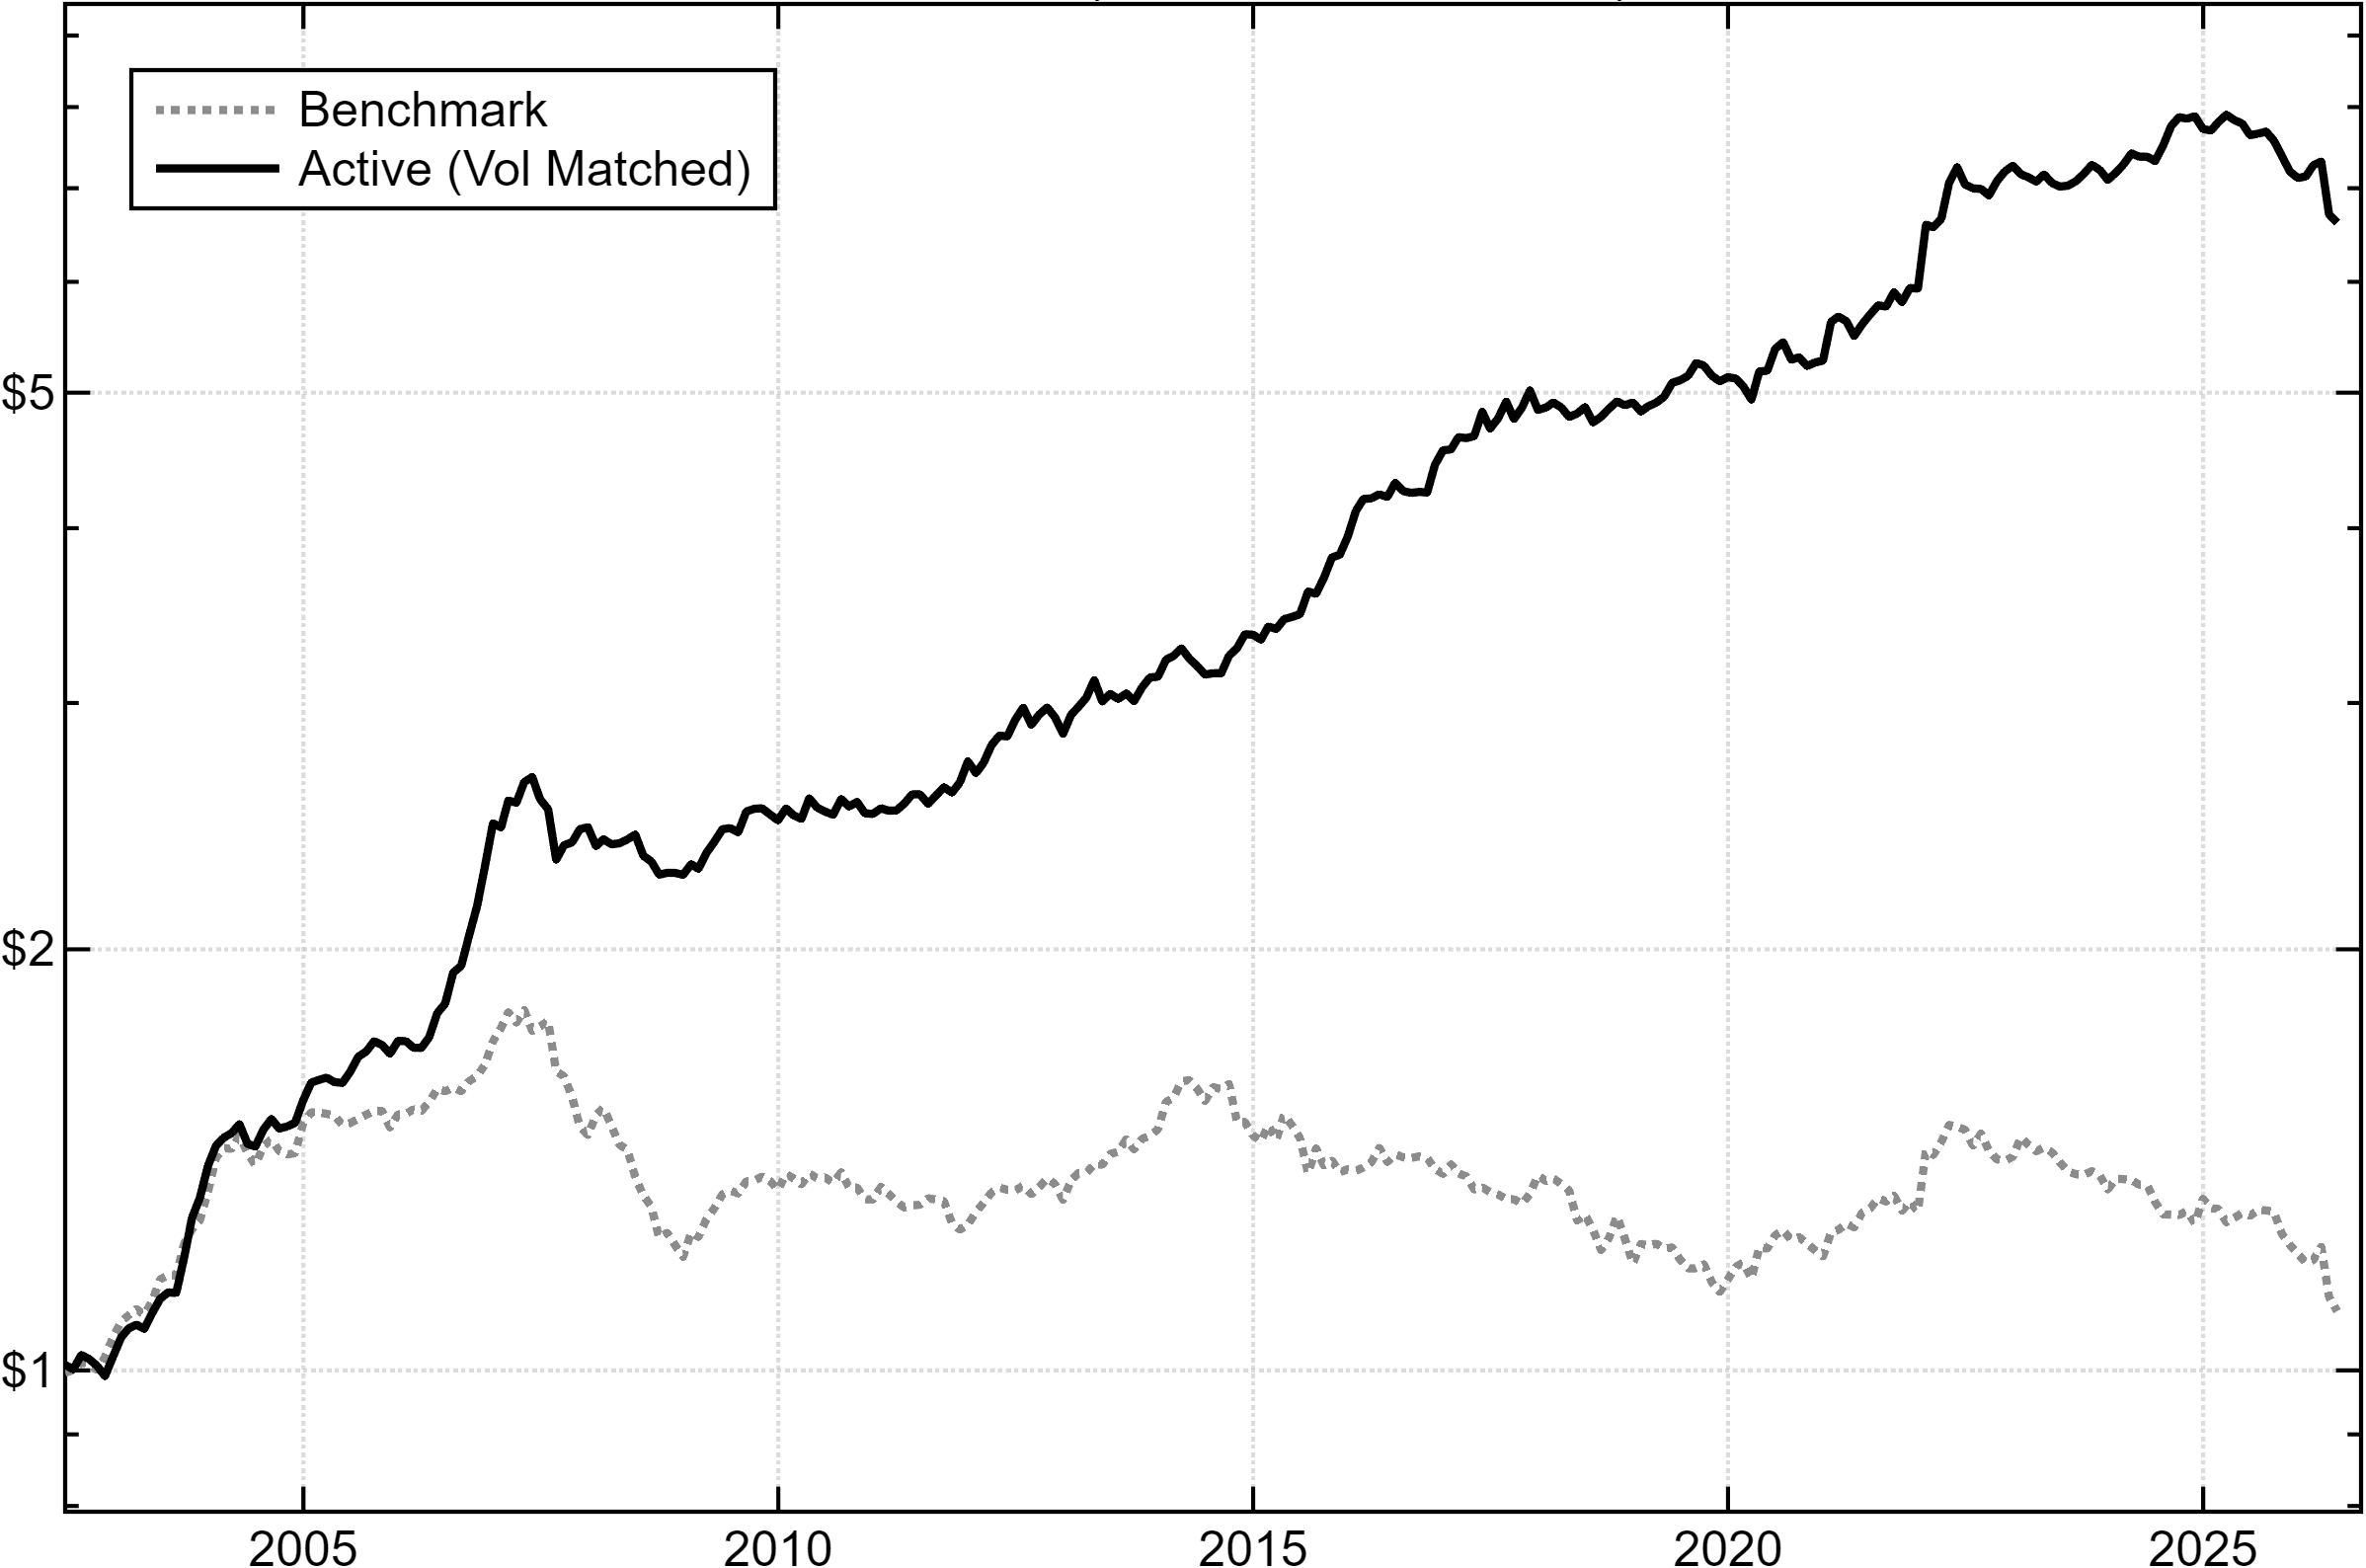
For investors seeking equity-style exposures that are easier to trade in practice, we believe this article offers some valuable insights.
Premium article
Read the full article
Buy this article on its own, or subscribe on Substack to read it together with all our premium research.
Questions about buying or your order? Email [email protected]